The government services sector offers access to companies whose revenues are driven by local or federal spending priorities, creating a varied source of exposure within a private credit portfolio.
Characteristics including long-term visibility, strong free cash flow, and growth opportunities make select government contractors attractive candidates for direct lending.
The complexities of government contracting, funding, and procurement create barriers to entry for private credit managers, making specialized experience and established relationships valuable in this sector.
The government services sector provides private credit investors exposure to an area of the economy that behaves differently than many traditional commercial industries. Rather than depending primarily on consumer spending or broader GDP growth, many government services companies derive revenue from government budgets and contracted services.
The distinct combination of recurring government demand, long-term revenue visibility, and cash-generative business models within the core middle market makes government services an attractive lending sector for PennantPark. As of June 30, 2026, PennantPark has deployed approximately $3.1 billion in this sector. Over 92% of these investments have been structured as first-lien senior secured debt.
That said, few private credit managers have the experience and knowledge needed to effectively participate in the sector.
Government services is a broad category referring to companies that provide goods, technology, expertise, and other services to federal, state, local, and international governments. PennantPark’s government sector exposure is primarily focused on companies supporting the U.S. federal government, particularly the Department of Defense (DoD).
Either integrated directly into the government’s day-to-day operations or working behind the scenes, these companies are contracted to provide critical support and supplies to various government entities.
For example, they help modernize government IT infrastructure, deliver cybersecurity capabilities, or provide specialized human capital. Others manufacture physical products or components used within larger government systems.
Private contractors perform a significant amount of the work required to support government operations. Many contracted employees work directly with and in major government facilities, including the Pentagon and NASA.
Because such a strong, ongoing dependency on private-sector companies exists, government services represent a substantive part of the economy. This provides direct lenders with access to companies that can exhibit several attractive credit characteristics:
Consistent demand: Government services revenue is tied more closely to government budgets and contracted programs than fluctuations in GDP. Defense spending, for example, has historically remained a federal priority across political administrations, providing a source of demand with different drivers than consumer-oriented or traditionally cyclical industries.
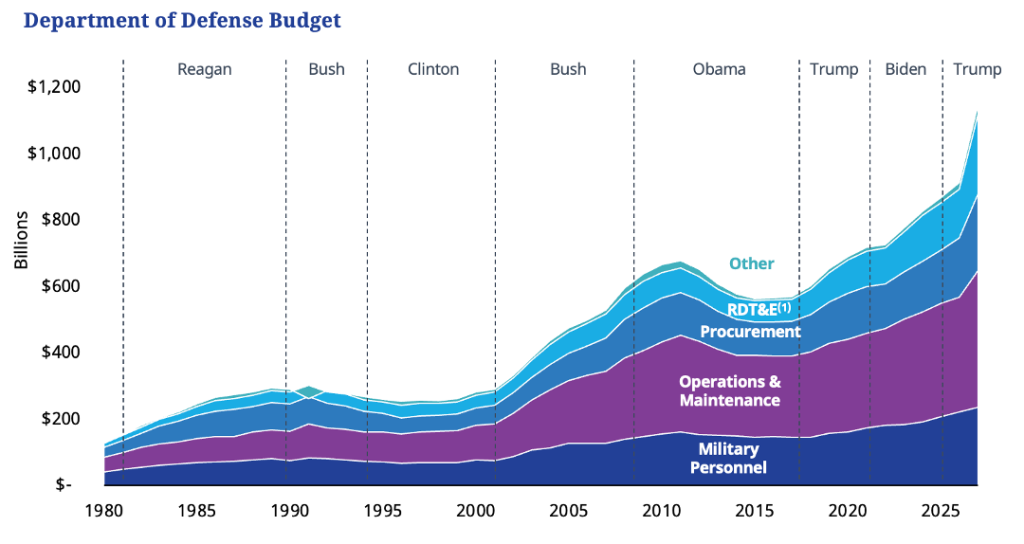
Sources: Whitehouse.gov: Outlays by Function and Subfunction: 1962 – 2031.
(1) Research, Development, Test, and Evaluation
Long-term revenue visibility: Government contracts are commonly structured as multi-year agreements, providing lenders with greater visibility into future revenue. Many programs also extend across changes in political leadership, particularly once the government has committed significant time and capital to an established mission or system.
Veteran-led leadership: Many government services companies are led by veterans and former government personnel who benefit from deep mission knowledge and firsthand experience navigating complex procurement processes. Their familiarity with agency priorities and contracting requirements is particularly valuable when building and growing businesses in such a highly specialized sector.
Attractive cash flow characteristics: Service-oriented government contractors often operate with relatively low fixed costs, capital expenditure requirements, and working capital needs. These characteristics can support stronger free cash flow conversion, helping borrowers make interest payments and repay principal.
Modernization opportunities: Government technology has historically advanced more slowly than its commercial counterpart, creating ongoing opportunities for modernization. We anticipate the Department of Defense and broader U.S. government will increasingly incorporate commercially oriented technology businesses as they seek faster and more efficient solutions, while state and local modernization may create additional opportunities.
A large, fragmented lending market: Thousands of middle market contractors provide products and services across government agencies and programs. Many pursue acquisitions to add capabilities, enter adjacent programs, or acquire specialized expertise, giving direct lenders opportunities to support companies through multiple stages of growth.
The same characteristics that make government services a differentiated lending opportunity also make it a complex sector to underwrite. To do so effectively, lenders need to understand government contract structures, funding sources, renewal characteristics, and the dependability of the underlying government.
For example, our underwriting considers scenarios involving tighter government spending, where we prioritize lower leverage and interest-coverage cushions designed to help protect lender capital.
Customer concentration also requires careful consideration. A contractor may serve multiple agencies or programs, yet the federal government likely remains its primary end customer. Service-oriented contractors also operate with relatively modest margins, reflecting the spending discipline that accompanies taxpayer-funded contracts.
More than 18 years of lending in the government services sector has deepened our understanding of these dynamics. Over time, we’ve developed relationships and a reputation of credibility among private equity sponsors and government services companies. Sponsors familiar with our ability to understand and execute these transactions may seek us out as a lending partner, contributing to a broader funnel of potential opportunities.
The government services sector illustrates why industry specialization can serve as an important distinction in private credit. To better serve investors and borrowers, we’ve developed a deep understanding of the forces driving its revenue, the structure and durability of its contracts, and the risks unique to its end market.
Nearly two decades of lending to government contractors has allowed PennantPark to establish a sourcing network and build a knowledge base within this important segment of the core middle market.
Government services provides access to companies with different economic drivers, long-term contracted revenue, and attractive cash flow characteristics. For PennantPark, experience within the sector gives us a strong foundation for identifying, underwriting, and selectively investing in those opportunities.
Considering incorporating private credit into your clients’ credit portfolios? We welcome a conversation. Please contact invest@pennantpark.com or the professionals listed below.
PennantPark was founded in 2007 as an independent middle market credit platform. The firm was founded by Art Penn, a private credit industry veteran that previously co-founded Apollo Investment Management. We have invested over $27 billion across multiple economic and credit cycles since inception, and we manage $10 billion in AUM today.1 PennantPark serves a broad range of sophisticated investors with product offerings that include business development companies, private capital funds, joint ventures, and other specialized funds.
Our highly experienced team primarily invests in the core middle market, targeting companies with earnings of $10 million to $50 million. These mid-sized companies are often overlooked by banks and large investment managers, resulting in senior secured loans that generally feature higher yields, lower leverage, and stronger lender protections when compared to the upper middle market and broadly syndicated loans. We focus on five key industry verticals where we have the most expertise and experience. These industries include healthcare, government services, business services, consumer, and software & technology2.


[1] Assets under management (“AUM”) is defined as the sum of gross asset values, unfunded commitments, joint ventures and undrawn available leverage for active funds as of 3/31/2026. Invested capital represents the cumulative sum of capital invested across the PennantPark platform since inception through 3/31/2026. Figures are rounded to the nearest billion.
[2] Past performance is not necessarily indicative of future results. Invested capital is at risk. The investment themes presented herein are solely the opinions of PennantPark. There is no assurance that these investment themes will continue to materialize. While government services contractors may benefit from long-term contracts and recurring demand, the sector is subject to risks including changes in government budgets, procurement delays, contract recompetes, agency concentration, funding disruptions, regulatory changes, labor shortages, and execution risks associated with acquisitions among other risk factors.
©2026 PennantPark Investment Advisers, LLC (‘PennantPark’) is an investment adviser registered with the US Securities and Exchange Commission (‘SEC’). Registration is not an endorsement by the SEC nor an indication of any specific level of skill. The material included in this document is intended for informational purposes only. Products or services referenced in this document may not be licensed in all jurisdictions, and unless otherwise indicated, no regulator or government authority has reviewed this document, or the merits of the products and services referenced herein. This document and the information contained herein has been made available in accordance with the restrictions and/or limitations implemented by applicable laws and regulations.
In considering the past performance information contained herein, recipients should bear in mind that past performance is not a guarantee, projection or prediction and it is not a guarantee or indication of future results. Invested capital is at risk. There can be no assurance that any product or service referenced herein will achieve comparable results, or that they will be able to implement their investment strategies or achieve their investment objectives.
An investment with PennantPark in any advised fund is suitable only for sophisticated investors and requires the financial ability and willingness to accept the risks and lack of liquidity that are characteristic of an investment in such funds. Investors must be prepared to bear such risks for an extended period. There can be no assurance that any investment will be profitable, not lose money, or achieve the other intended purposes for which they are made. Investing with PennantPark will expose the investor to various risks including, but not limed to, the following: 1) Lack of Liquidity Risks including lack of permitted withdrawals, lack of secondary market, and lack of transferability 2) Interest Rate Volatility Risks 3) Use of Leverage Risks 4) Securitization Risks 5) Credit Market Disruption Risks 6) Investing within a Highly Competitive Market Risks 7) Default by Borrowers Risks 8) Recovery on Bad Debt Risks including cost of recovery 9) International Market Exposure Risks 10) Inflation and Deflation Exposure Risks. This is not intended to be a complete description of the risks of investing with PennantPark. 11) Political and Government Policy Risks.
The information contained here does not constitute, and is not intended to constitute, an offer of securities and accordingly should not be construed as such. Any such offering of a Pennant Park fund can be made only at the time a qualified offeree receives a confidential private offering memorandum, prospectus and/or other operative documents which contain significant details with respect to risks and which should be carefully read. All information contained in this presentation is qualified in its entirety by each fund’s operative documents. Investors should rely on their own examination of the potential risks and rewards. The firm brochure (Form ADV 2A) is available online at www.adviserinfo.sec.gov or upon request and also discusses these and other important risk factors and considerations that should be carefully evaluated before making an investment. Information in this document does not constitute legal, tax, or investment advice. Before acting on any information in this document, current and prospective investors should inform themselves of and observe all applicable laws, rules and regulations of any relevant jurisdictions or obtain independent tax, legal, or investment advice.
This document may not be reproduced and may not be redistributed to any party without prior written consent. Statements in this document are made as of the date hereof unless stated otherwise herein, and neither the delivery of this document at any time, nor any sale hereunder, shall under any circumstances create an implication that the information contained herein is correct as of any time after such date. Certain information contained herein concerning economic trends and performance is based on or derived from information provided by independent third-party sources. PennantPark believes that such information is accurate and that the sources from which it has been obtained are reliable. PennantPark cannot guarantee the accuracy of such information, however, and has not independently verified the assumptions on which such information is based. Certain statements contained in this document, including without limitation, statements containing the words “believes,” “anticipates,” “intends,” “expects,” and words of similar import constitute “forward looking statements.” Additionally, any forecasts and estimates provided herein are forward-looking statements. Such statements and other forward-looking statements are based on available information and the views of PennantPark as of the date hereof. Accordingly, such statements are inherently speculative as they are based on assumptions that may involve known and unknown risks and uncertainties. Actual results and events may differ materially from those in any forward-looking statements. Further, any opinions or analysis expressed are the current opinions or analysis of PennantPark only, are not guaranteed, and may be subject to change, without notice. There is no undertaking to update any of the information in this document. No person has been authorized in connection with this document to give any information or to make any representations other than as contained in this document and, if given or made, such information or representation must not be relied upon as having been authorized by PennantPark or PennantPark’s affiliates.